
ENSAE Paris × UC Berkeley MFE
Welcome to my website
Engineering student with a deep passion for portfolio management and quantitative investing, working toward becoming a successful portfolio manager.
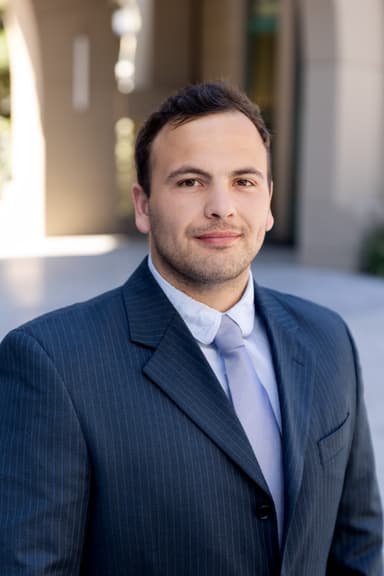
My name is Elouan Bahri. I'm an ENSAE Paris engineering student and Master in Financial Engineering (MFE) candidate at UC Berkeley, graduating in February 2027. Portfolio management and quantitative investing are what drive me, and my long-term goal is to build a career as a successful portfolio manager — bringing strong determination, energy, and a fast-learning mindset to every step along the way. I also built this website using Claude — a small demonstration of my ability to create new things with AI.
- Graduating
- Feb 2027
- Based in
- the USA
- Focus
- Portfolio Management & Quant Finance
Education & Experience
Where I've studied and worked.
Education
University of California, Berkeley — Haas School of Business
Expected March 2027Master of Financial Engineering · Berkeley, CA, USA
ENSAE Paris — Polytechnic Institute of Paris
Expected upon completion of the MFEMaster of Science in Statistics, Finance and Data Science · Paris, France
ENSAE Paris — Polytechnic Institute of Paris
November 2024Bachelor of Science in Economics and Applied Mathematics · Paris, France
- GPA: 4.0/4.0
Experience
UBS Investment Bank
Oct 2026 – Jan 2027Incoming Off-Cycle Intern — Global Markets, Derivatives & Solutions · New York, NY, USA
- Joining the New York office to actively contribute to derivative structuring and trading operations.
Barclays Investment Bank
Jun 2025 – Dec 2025Rates Strat Intern · Paris, France
- Researched and backtested SSA bond pair trades using OLS residuals, optimizing entries with Z-spread, duration, convexity, and repo rates — yielding a 1.52 Sharpe Ratio on the SSA desk.
- Engineered an LSTM model to predict RFQ hit probability (0.72 AUC), generating a live probability matrix by DV01 and client industry to optimize skew and capture alpha.
- Built a modular Python backtesting framework computing Sharpe Ratio, PnL/trade, carry, and holding time.
- Developed real-time risk engines (AG Grid/Charts) giving EM, SSA, and inflation desks instant DV01 exposure and RFQ analytics.
Galileo Global Education
Jun 2024 – Sep 2024Data Analyst Intern · Paris, France
- Developed Streamlit web apps with automated data cleaning (Pandas) and PDF extraction pipelines (PDFplumber, Tesseract OCR), cutting manual processing time from 3 days to 20 minutes.
- Built a neural network–based NLP model for sentiment analysis on alumni feedback to evaluate program effectiveness.
Selected projects
A few things I've built recently.
ChronoStrike
An interactive equity options learning tool — click through the Greeks (delta, gamma, theta, vega, rho) and watch live Black-Scholes charts respond instantly as you drag the price, volatility, and time-to-expiry sliders.
Revoscope
A full-stack investing dashboard — P&L, allocation, dividends, and live prices merged across Revolut CSV imports, Binance, and Interactive Brokers accounts.
Spinoff Index Arbitrage
A beta-hedged, market-neutral long strategy on post-spinoff parent stocks (0.69 Sharpe), refined with leakage-free decision tree and logistic regression models estimating index-inclusion probabilities — raising Sharpe to 1.29 via probability-weighted position sizing.
Crypto Price Prediction
A modular framework comparing classical time series models (ARIMA, GARCH) against ML models (LSTM/GRU, XGBoost, LLMs) for cryptocurrency forecasting, with a live-traded strategy yielding a 25% net return over 3 months.
ENS-CFM Data Challenge
A stock-identification classifier for the ENS/CFM challenge — inferring which of 158 stocks a piece of anonymized tick-by-tick order-book data belongs to, ranking 16th on the private leaderboard (10% above benchmark).
C++ PDE Option Pricer
A C++ implementation of numerical PDE solvers for pricing European and digital call/put options under the Black-Scholes-Merton framework, outputting price grids for visualization.
Bonus: if you want to train mental math and sequences, click here.
Skills
Tools and areas I work with regularly.
Quantitative Finance
- Derivatives Pricing
- Portfolio Theory
- Relative Value Strategies
- Bloomberg Terminal
Mathematics & Statistics
- Probability Theory
- Statistics & Econometrics
- Time-Series Analysis
- Stochastic Calculus
Machine Learning
- TensorFlow
- PyTorch
- scikit-learn
- Deep Learning (LSTM/GRU)
Trading & Tools
- Algorithmic Trading
- Backtesting
- Python
- SQL
Let's talk
Open to conversations about portfolio management, quantitative investing, and opportunities. Reach out any time.